How to Avoid Paying Tax on Your Pension: Tax-Free Lump Sums and Drawdown Rules
 • October 25, 2025
Last Updated: 26.10.2026
Pension tax can take a significant amount out of your retirement savings if withdrawals are made without considering the timing, amount and wider tax position.
The good news is that UK pension rules provide several legitimate ways to reduce the amount of Income Tax you pay.
If you are trying to understand how to avoid paying tax on your pension, the aim should not be to hide pension income from HMRC.
Instead, effective pension tax planning involves using your tax-free pension entitlement, Personal Allowance and Income Tax bands efficiently while avoiding withdrawals that create unnecessary tax charges.
For the 2026/27 tax year, the standard Personal Allowance remains £12,570. The full new State Pension is £241.30 per week, equivalent to £12,547.60 over 52 weeks.
This means someone receiving the full new State Pension has only a small amount of their standard Personal Allowance remaining before other taxable pension income can start creating an Income Tax liability.
That makes withdrawal planning increasingly important for pensioners with workplace pensions, personal pensions, drawdown arrangements or other income.
How Much Retirement Income Can You Receive Before Tax Starts?
For most people in England, Wales and Northern Ireland, the standard Personal Allowance for 2026/27 is £12,570.
Income above this level can become taxable depending on the type of income received and other allowances available.
The main Income Tax bands for 2026/27 are:
| Income Level | Income Tax Rate |
|---|---|
| Up To £12,570 | 0% Within Standard Personal Allowance |
| £12,571 To £50,270 | 20% |
| £50,271 To £125,140 | 40% |
| Above £125,140 | 45% |
Scottish taxpayers have different Income Tax bands for pension and other non-savings, non-dividend income.
The frozen Personal Allowance is becoming particularly important for pensioners because the State Pension continues to rise while the tax-free threshold remains unchanged.
The wider effect of frozen UK tax brackets in 2026 means more retirement income can gradually move into the taxable range even without a change in headline tax rates.
Someone receiving the full new State Pension of £12,547.60 in 2026/27 would have only £22.40 of a standard £12,570
Personal Allowance remaining, assuming there are no other adjustments or allowances. The State Pension itself is taxable even though tax is not normally deducted before it is paid.
This helps explain why more pensioners are being drawn into Income Tax as State Pension payments increase.
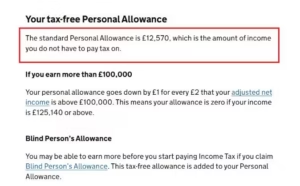
GOV.UK confirms the £12,570 Personal Allowance and current Income Tax bands for the 2026/27 tax year.
Which Parts Of Your Pension Are Tax-Free And Which Are Taxable?
Not every pound withdrawn from a pension receives the same tax treatment.
With most defined contribution pensions, you can normally take up to 25% of your pension benefits tax-free, subject to the available Lump Sum Allowance.
The standard Lump Sum Allowance remains £268,275 for 2026/27, although people with certain historic protections may have different limits.
The remaining pension money is generally taxable when it is withdrawn.
For example, if you withdraw £20,000 using an arrangement where 25% of each withdrawal is tax-free:
- Tax-Free Portion: £5,000
- Taxable Portion: £15,000
- Actual Tax Due: Depends On Your Other Income And Tax Band
However, it is important not to assume every future withdrawal will automatically be 25% tax-free.
If you take your 25% Pension Commencement Lump Sum first and move the remaining 75% into flexi-access drawdown, withdrawals from that crystallised drawdown fund will generally be taxable.
Defined benefit pensions work differently. Regular income from a final salary or career-average pension is normally taxable pension income rather than a pension pot from which 25% of every monthly payment is tax-free.
The State Pension is also taxable income. HMRC normally considers your overall taxable income when determining whether tax is due.
How Can You Reduce Tax When Withdrawing From Your Pension?
There is no single pension withdrawal strategy that produces the lowest tax bill for everyone. Your State Pension, employment income, savings, rental income and other pensions can all change the calculation.
Several methods can, however, help prevent avoidable tax.
Use Your Personal Allowance
Before making a taxable pension withdrawal, calculate how much of your Personal Allowance has already been used.
Someone who has not yet started receiving the State Pension and has little other taxable income might have significantly more Personal Allowance available than someone receiving the full State Pension.
Withdrawals can then be planned around the available allowance and tax bands rather than choosing an arbitrary amount from the pension pot.
People with adjusted net income above £100,000 should be particularly careful. The Personal Allowance falls by £1 for every £2 of adjusted net income over £100,000 and disappears entirely at £125,140.
A large pension withdrawal can therefore have a bigger tax effect than simply moving part of the withdrawal into the 40% band.
Spread Withdrawals Across Tax Years
Taking £80,000 of taxable pension income in one tax year can produce a very different result from taking smaller amounts over several tax years.
A large one-off withdrawal may move part of your income into a higher tax band. Spreading the withdrawal can potentially allow you to use more than one year’s Personal Allowance and basic-rate band.
This does not mean that splitting withdrawals is always the best choice. Future tax bands, investment performance, living costs and pension charges should also be considered.
People using drawdown should also examine provider fees because repeated withdrawals, investment performance and changing fund values can affect overall retirement costs.
These factors are particularly relevant when comparing pension income strategies and drawdown charges.
Combine Pension Income With ISA Withdrawals
ISA withdrawals do not normally count as taxable income. This makes ISA savings potentially useful when trying to avoid unnecessarily large taxable pension withdrawals.
For example, someone needing £30,000 for annual spending might not necessarily need to withdraw the entire amount as taxable pension income. Depending on their finances, part could come from pension income and part from existing ISA savings.
The important distinction is that withdrawing money from an ISA is generally tax-free, while withdrawing the taxable portion of a pension can use Personal Allowance and move income into higher tax bands.
However, pensions and ISAs have different investment, estate-planning and access characteristics. Using an ISA first is therefore not automatically the correct strategy for every retiree.
Avoid Large Unnecessary Lump Sums
Taking an entire pension pot simply because it is available can result in a substantial Income Tax bill.
If a £100,000 pension is withdrawn using the usual 25% tax-free treatment, £25,000 may be tax-free while £75,000 can be taxable income.
Adding that £75,000 to State Pension, earnings, rental income or other taxable income can push a large portion into the higher-rate band.
Money removed from the pension also loses the pension wrapper and may become part of ordinary savings or investments.
The decision should therefore be based on what the money is needed for rather than the maximum amount the pension provider allows you to withdraw.
What Pension Practices Could Lead To Tax Charges Or Penalties?
Tax planning is legal. Breaking pension tax rules or failing to deal correctly with a resulting tax liability is different.
Certain practices can create significant additional tax charges.
Taking Unauthorised Pension Payments
Accessing pension savings before the permitted minimum pension age can result in an unauthorised payment unless a specific exception applies, such as qualifying ill health or a protected pension age.
The normal minimum pension age is generally 55 during 2026/27 and is due to rise to 57 from 6 April 2028 for most people.
HMRC states that unauthorised pension payments can face a 40% unauthorised payments charge. An additional 15% surcharge can apply in certain cases, taking the member’s total tax charge to as much as 55%.
Offers claiming to provide loans or methods for unlocking pension savings early should therefore be treated with considerable caution.
Recycling Tax-Free Pension Cash
Taking tax-free pension cash and deliberately using it to make significantly increased pension contributions can fall within HMRC’s pension commencement lump sum recycling rules when the relevant conditions are satisfied.
The rules are designed to prevent people repeatedly extracting tax-free pension cash and reinvesting it to obtain additional pension tax relief.
Where the statutory recycling conditions are met, the pension commencement lump sum can be treated as an unauthorised payment.
Not every contribution made after receiving tax-free cash is automatically recycling. The detailed circumstances, amounts and intention behind the arrangement matter.
Exceeding Pension Allowances
The standard pension annual allowance for 2026/27 is £60,000, although the amount can be lower for some higher earners and people who have triggered the Money Purchase Annual Allowance.
Exceeding the relevant allowance does not automatically mean you have committed an offence. However, an Annual Allowance tax charge can arise.
People who need to report and pay pension tax charges should also meet the relevant HMRC filing and payment requirements. Late reporting or payment can create additional interest or penalties depending on the circumstances.
What Does Martin Lewis Advise Before Taking Money From Your Pension?
Martin Lewis and MoneySavingExpert have repeatedly highlighted the importance of understanding the tax consequences before withdrawing pension money.
One of the central points in MoneySavingExpert’s pension guidance is that withdrawing too much taxable pension income in one year can move someone into a higher tax band.
Its guidance therefore stresses the importance of staging withdrawals where appropriate rather than automatically taking a large amount at once.
The guidance also makes an important distinction between taking tax-free cash and taking taxable flexible pension income.
MoneySavingExpert explains that:
- Taking Only Tax-Free Cash: Normally Does Not Trigger The MPAA
- Taking Taxable Flexible Income: Usually Can Trigger The MPAA
- Large Withdrawals: Can Push Income Into A Higher Tax Band
- First Flexible Withdrawals: Can Be Subject To Emergency Tax
- Getting Guidance First: Can Help Prevent Irreversible Pension Decisions
Martin Lewis’s guidance also encourages people to use free pension guidance before making major withdrawal decisions, particularly where pension freedoms create several different options.
Another important warning is that accessing a pension simply because you have reached the minimum age may be unnecessary.
Leaving money inside a pension can allow it to remain invested until it is genuinely required.
Could Taking Pension Income Trigger The Money Purchase Annual Allowance?
The Money Purchase Annual Allowance, or MPAA, is one of the most important rules for people who access a pension while continuing to work and contribute to defined contribution pensions.
The normal pension Annual Allowance is £60,000 for 2026/27, subject to individual circumstances.
However, once certain flexible taxable pension benefits have been accessed, the amount that can generally be contributed to money purchase pensions under the MPAA becomes £10,000.
For example, someone aged 58 may still be employed and contributing heavily to a workplace defined contribution pension.
If they flexibly withdraw taxable income from another pension without understanding the MPAA, their future contribution position can change substantially.
Taking only tax-free pension cash without taking taxable drawdown income does not normally trigger the MPAA. Neither does simply receiving income from a defined benefit pension.
MoneySavingExpert also notes specific exceptions involving normal lifetime annuities and certain small pension pots.
The key point is that accessing a pension and flexibly accessing taxable pension income are not always the same event for MPAA purposes.
Money Purchase Annual Allowance:
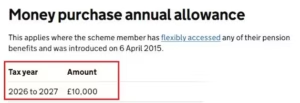 standard Annual Allowance:
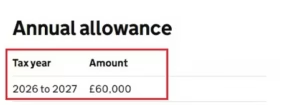
HMRC confirms the £10,000 Money Purchase Annual Allowance and £60,000 standard Annual Allowance for 2026/27.
Should You Take Your Pension In One Go Or Over Several Years?
Taking a pension in one payment can be convenient, but it can also concentrate taxable income into a single tax year.
Consider an illustrative retiree with a £100,000 defined contribution pension who also receives the full 2026/27 new State Pension of £12,547.60.
If the entire pension is withdrawn under a structure where £25,000 is tax-free and £75,000 is taxable, taxable income for that year would become:
£75,000 + £12,547.60 = £87,547.60
Using the standard 2026/27 Personal Allowance and England, Wales and Northern Ireland tax bands for illustration, the approximate Income Tax would be:
- Personal Allowance: £12,570
- Income Taxed At 20%: £37,700
- Income Taxed At 40%: £37,277.60
- Approximate Income Tax: £22,451
Now consider an illustrative strategy in which £20,000 of the pension is accessed annually for five years and 25% of each payment qualifies as tax-free cash.
Each year’s £20,000 withdrawal would consist of:
- Tax-Free Cash: £5,000
- Taxable Pension Income: £15,000
- State Pension: £12,547.60
- Total Taxable Income Before Personal Allowance: £27,547.60
Applying the same 2026/27 rates purely for comparison gives approximately £2,996 of Income Tax each year.
| Withdrawal Strategy | Approximate Tax Using 2026/27 Rates |
|---|---|
| £100,000 Pension Taken In One Year | £22,451 |
| £20,000 Taken Annually For Five Years | £14,978 Total |
| Illustrative Difference | About £7,473 |
This comparison is illustrative rather than a forecast. Income Tax rates, State Pension payments and personal circumstances can change over five years.
The example nevertheless demonstrates why the timing of pension withdrawals can matter just as much as the size of the pension pot.
How Can You Avoid Emergency Tax On Pension Withdrawals?
Flexible pension withdrawals can sometimes be taxed using an emergency tax code, particularly when HMRC or the pension provider does not yet have enough information to calculate the appropriate tax deduction.
For 2026/27, emergency codes include 1257L W1, 1257L M1 and 1257L X.
A Month 1 or Week 1 code effectively looks at the payment in isolation rather than fully considering previous income across the tax year. This can result in too much tax being deducted from a large one-off pension withdrawal.
Checking the tax code used by the pension provider is therefore important. A wider understanding of why HMRC changes tax codes can also help pensioners identify whether another income source, previous underpayment or incorrect HMRC estimate is affecting the code.
You may not always be able to prevent emergency tax being deducted from a first flexible withdrawal. However, you do not necessarily have to wait until the end of the tax year to recover an overpayment.
HMRC provides different refund routes depending on what happened:
- P55: Generally Used If You Flexibly Accessed Part Of Your Pension And Have Not Emptied The Pot
- P53Z: Generally Used After Flexibly Accessing The Whole Pension Pot When You Have Other PAYE Or Pension Income
- P50Z: Generally Used After Taking The Whole Pension Pot When You Have Stopped Working And Meet The Relevant Conditions
HMRC introduced updated guidance in October 2026 explaining the different pension refund routes and warns that using the wrong form can delay repayment.
MoneySavingExpert also recommends dealing with a refund claim promptly where excessive tax is deducted rather than unnecessarily waiting until the tax year finishes.
What Other Income Counts When Your Pension Tax Is Calculated?
Pension withdrawals cannot be considered in isolation because Income Tax generally depends on your total taxable income.
Income that may need to be considered includes:
- State Pension
- Private Pension Income
- Defined Benefit Pension Income
- Annuity Income
- Employment Income
- Self-Employment Profits
- Rental Income
- Taxable Savings Interest
- Dividend Income
- Certain Taxable State Benefits
Savings and dividend income have their own allowances and tax rules, so the exact calculation can differ from ordinary pension income.
This becomes particularly important for someone who continues working after reaching pension access age.
A pension withdrawal that would remain within the basic-rate band for a fully retired person could move a working individual into the higher-rate band.
Before making a large withdrawal, total expected income for the entire tax year should therefore be estimated rather than looking only at the pension payment.
Can Taking Pension Money Affect Means-Tested Benefits?
Tax-free pension cash is not necessarily irrelevant for benefit purposes simply because no Income Tax is due on it.
Means-tested benefit systems can consider income and capital under their own rules.
Money taken from a pension and retained in a bank or savings account may therefore affect an assessment differently from money that remains inside a pension.
Regular pension income may also be taken into account when entitlement to certain means-tested benefits is calculated.
The precise effect depends on the benefit being claimed, the claimant’s age, household circumstances and the way pension money is accessed.
This means someone receiving Pension Credit or another means-tested benefit should not assume that withdrawing the maximum tax-free pension cash will leave their benefit entitlement unchanged.
Checking the relevant benefit rules before making a substantial withdrawal can prevent an unexpected reduction in support.
How Will Pension Inheritance Tax Change From April 2027?
One of the biggest retirement tax changes ahead concerns unused pension funds after death.
Finance Act 2026 legislated reforms that will bring most unused pension funds and pension death benefits within the value of a person’s estate for Inheritance Tax purposes for deaths occurring on or after 6 April 2027.
This does not mean every pension will automatically face 40% Inheritance Tax.
Whether tax is due will depend on factors including:
- Total Estate Value
- Available IHT Allowances
- Spouse Or Civil Partner Exemptions
- Type Of Pension Benefit
- Identity Of The Beneficiary
- Other Assets In The Estate
Certain payments, including qualifying death-in-service benefits from registered pension schemes, are excluded from the new framework.
The rules also make administration more important. Personal representatives will generally be responsible for reporting and paying IHT due on relevant pension wealth, with information needing to pass between representatives, pension schemes and beneficiaries.
The impact of the forthcoming change is examined further in the UK’s 2027 pension inheritance tax changes, including how unused pension funds may interact with property, investments and other estate assets.
Importantly, withdrawing a pension simply to keep it outside the new pension rules may not solve the problem. The withdrawal itself can create Income Tax, while cash retained until death can still form part of the estate.
Estate planning should therefore consider both Income Tax during retirement and Inheritance Tax after death rather than focusing on only one tax.
Frequently Asked Questions
Can I Legally Avoid Paying Tax On My Pension?
Yes, some pension income can legally be received without Income Tax by using available tax-free pension cash and Personal Allowance. However, most people with taxable retirement income above their available allowances will eventually have some Income Tax to pay.
How Much Can I Take From My Pension Tax-Free?
You can generally take up to 25% of eligible defined contribution pension benefits tax-free, subject to your available Lump Sum Allowance. The standard Lump Sum Allowance is £268,275 in 2026/27, although protected allowances can apply in some cases.
Can I Take 25% Of My Pension Tax-Free Every Year?
There is not a new 25% allowance every tax year. The tax-free amount relates to your eligible pension benefits and available Lump Sum Allowance. Depending on the withdrawal method, tax-free cash can sometimes be phased rather than taken all at once.
What Happens If I Access My Pension Too Early?
An unauthorised early pension payment can create substantial tax charges. HMRC states that the combined unauthorised payment charge and surcharge can reach 55% in certain circumstances.
How Can I Avoid Paying 40% Tax On My Pension?
Keeping taxable withdrawals within the basic-rate band where circumstances allow can prevent some pension income entering the 40% band. Spreading withdrawals across tax years and combining pension income with tax-free savings may help, although the best approach depends on total income.
Will I Pay Emergency Tax On My First Pension Withdrawal?
You may. Flexible pension payments can initially be taxed using an emergency Week 1 or Month 1 basis. If too much tax is deducted, HMRC provides routes for claiming an in-year refund.
Does Taking Pension Income Trigger The MPAA?
Taking taxable income flexibly from a defined contribution pension will usually trigger the Money Purchase Annual Allowance. Simply taking eligible tax-free cash without taxable flexible income does not normally trigger it. The MPAA is £10,000 for 2026/27.