Universal Credit Under 25 Penalty: 2026/27 Rates, Sanctions And Rules
 • June 19, 2026
Last Updated: 25.09.2026
The Universal Credit under-25 penalty commonly refers to the lower standard allowance paid to many Universal Credit claimants below the age of 25. It is not an official penalty or sanction imposed because someone has broken benefit rules.
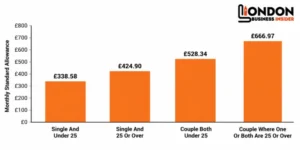
In 2026/27, a single claimant under 25 receives a standard allowance of £338.58 per month, while a single claimant aged 25 or over receives £424.90. That creates a difference of £86.32 each month before other Universal Credit elements, earnings and deductions are considered.
Actual Universal Credit sanctions work differently. They can reduce a claimant’s standard allowance when certain work-related requirements are not met without a good reason.
Understanding the difference is important because an under-25 claimant can be affected by the lower age-based allowance and a separate sanction at the same time.
How Much Is Universal Credit Under 25 In 2026/27?
Universal Credit standard allowance rates increased from April 2026.
Household Circumstances Monthly Standard Allowance
Single And Under 25 £338.58
Single And 25 Or Over £424.90
Couple Both Under 25 £528.34
Couple Where One Or Both Are 25 Or Over £666.97
The current amounts are also set out in MoneyHelper’s information on Universal Credit payment rates, which explains that additional amounts may be available for children, childcare, housing, caring responsibilities and qualifying health conditions.
The figures above are standard allowances only. They do not necessarily represent the claimant’s final Universal Credit payment.
Earnings, savings, housing circumstances, children, childcare costs and deductions can all affect the amount eventually paid.
How Much Less Do Under-25 Claimants Receive?
A single claimant under 25 receives £338.58 per month, compared with £424.90 for someone aged 25 or over.
That creates a difference of:
£424.90 – £338.58 = £86.32 per month
Over 12 months, the difference is approximately £1,035.84.
For couples, the difference is larger. Where both claimants are under 25, the standard allowance is £528.34 per month. If one or both partners are aged 25 or over, it rises to £666.97.
The monthly difference is £138.63, which equals approximately £1,663.56 over 12 months.
These calculations explain why the age-based difference is sometimes described as a penalty, even though it is technically part of the normal Universal Credit entitlement structure.
Why Do Under-25s Get Less Universal Credit?
The Universal Credit system has different standard allowance rates according to age and household circumstances.
The age distinction reflects a long-standing approach within parts of the UK benefits system where younger adults have sometimes received lower personal allowance rates.
One argument for lower rates is that younger adults may be more likely to live with parents, relatives or in shared accommodation, which could reduce some household costs.
However, this does not apply to every young claimant. Someone aged 21 who rents independently may still need to pay for accommodation, utilities, groceries, transport and other essential expenses.
This has contributed to continuing debate about whether age remains an appropriate basis for different standard allowance levels.
Regardless of that wider debate, the under-25 rate remains part of the Universal Credit calculation in 2026/27.
Is The Universal Credit Under 25 Penalty A DWP Sanction?
No. The age-based Universal Credit rate and a DWP sanction are different.
The lower under-25 standard allowance applies automatically when the relevant age and household conditions are met.
A sanction can occur when the DWP decides a claimant has failed to meet certain responsibilities in their claimant commitment without a good reason.
Under-25 Standard Allowance Universal Credit Sanction
Based On Age Based On Certain Claimant Requirements
Part Of Normal UC Calculation Reduction Following A Sanction Decision
Does Not Mean Rules Were Broken Can Follow Failure To Meet Requirements
Applies Automatically Where Relevant Depends On Individual Circumstances
Continues While Age Rules Apply Usually Applies For A Defined Period
An under-25 claimant can therefore receive the lower standard allowance while also being sanctioned separately.
How Much Is A Universal Credit Sanction If You Are Under 25?
For 2026/27, a single Universal Credit claimant under 25 can have £11.10 per day deducted when the full sanction rate applies.
The current daily sanction rates are:
Claimant Circumstances 100% Daily Reduction 40% Daily Reduction
Single Under 25 £11.10 £4.40
Single 25 Or Over £13.90 £5.50
Couple Both Under 25, Per Sanctioned Claimant £8.60 £3.40
Couple With One Or Both Aged 25+, Per Sanctioned Claimant £10.90 £4.30
The DWP’s current Universal Credit sanction rules explain the daily reduction rates, sanction levels and circumstances in which payments can be reduced.
They also confirm that additional amounts for eligible children and housing costs continue to be included when the standard allowance is sanctioned.
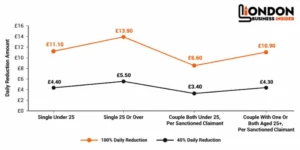
The 40% reduction rate applies in specific circumstances rather than automatically to every claimant.
This can include some people whose only work-related responsibility is attending appointments. Different rules also apply to claimants aged 16 or 17.
How Long Can A Universal Credit Sanction Last?
The duration of a sanction depends on which requirement was not met and whether previous sanctions apply.
Sanction Level Typical Duration For Adults
Lowest Level Until The Claimant Takes The Required Action
Low Level Compliance Period Plus Additional Days
Medium Level Normally 28 Days For A First Relevant Sanction
Repeat Medium Level Can Increase To 91 Days
High Level Normally 91 Days
Repeat High Level Can Reach 182 Days
A low-level sanction can continue until the claimant completes the required activity, with additional days potentially added.
A medium-level sanction normally lasts 28 days for a first relevant sanction during the applicable period. Repeat cases can result in a longer sanction.
High-level sanctions can be considerably longer, particularly when there has been a previous high-level sanction.
The exact period should appear in the claimant’s Universal Credit account or decision notification.
What Can Cause A Universal Credit Sanction?
Universal Credit sanctions are usually connected to responsibilities contained in a claimant commitment. Not every claimant has the same responsibilities because requirements depend on circumstances.
Common situations that can potentially lead to sanctions include:
- Missing Appointments: Failing to attend or participate in a required Jobcentre appointment without good reason
- Not Searching For Work: Failing to complete agreed work-search activities where these requirements apply
- Missing Training: Not attending compulsory employment preparation or training
- Not Providing Evidence: Failing to provide requested evidence relating to work-related activities
- Refusing Suitable Employment: Failing to accept suitable work without good reason
- Leaving Employment: Voluntarily leaving employment or losing work because of misconduct in circumstances covered by sanction rules
A missed appointment does not necessarily mean a sanction will automatically be applied.
If illness, an emergency, caring responsibilities or another genuine problem prevents someone from meeting a requirement, they should contact their work coach as soon as possible and explain what happened.
Keeping supporting evidence can also be important if the decision is later disputed.
Does A Universal Credit Sanction Affect Housing Or Child Payments?
A Universal Credit sanction primarily reduces the claimant’s standard allowance.
Additional amounts for eligible children and housing costs are not themselves removed simply because the standard allowance has been sanctioned.
However, the total amount reaching the claimant’s bank account can still vary because Universal Credit may also be affected by earnings, previous advances, overpayment deductions and other adjustments.
Claimants should therefore check their Universal Credit statement rather than assuming the entire reduction comes from the sanction.
This is particularly important for young renters and parents because their Universal Credit awards may include several different elements.
Can You Get A Hardship Payment During A Sanction?
A claimant who cannot afford essential living costs because of a Universal Credit sanction may be able to request a recoverable hardship payment.
The payment is intended for people who are struggling to meet essential costs such as food, heating, hygiene and housing-related expenses.
Eligibility conditions apply. A claimant may need to demonstrate that they have taken reasonable steps to reduce non-essential spending and that they cannot meet basic needs without additional support.
For Universal Credit claimants, hardship payments normally have to be repaid. Repayments are generally taken from later Universal Credit payments.
This means a hardship payment can provide immediate support during a sanction, but it may reduce future disposable income while the amount is being recovered.
Can You Challenge A Universal Credit Sanction?
A claimant does not have to accept a sanction decision without question.
If someone believes the DWP made the wrong decision, they can normally request a Mandatory Reconsideration.
This asks the DWP to examine the decision again.
Evidence can be particularly useful. Depending on the circumstances, this might include medical records, proof of an emergency, correspondence with a work coach, transport disruption evidence or records showing that a required activity was completed.
If the decision remains unchanged following Mandatory Reconsideration, the claimant may be able to appeal to an independent tribunal.
Claimants should pay attention to the deadline shown on their decision because delaying a challenge can make the process more complicated.
Does Being Under 25 Affect Universal Credit Housing Support?
The standard allowance uses an age threshold of 25, but private-renting housing rules can use a different threshold.
For many single private renters under 35 who have no dependent children,
Universal Credit housing support is generally based on the Shared Accommodation Rate rather than the Local Housing Allowance rate for a self-contained one-bedroom property.
This means some people under 25 can face both a lower Universal Credit standard allowance and restrictions affecting the amount of housing support available.
There are important exceptions.
Shelter’s explanation of Local Housing Allowance for private renters under 35 covers circumstances where a claimant may qualify for a higher housing rate, including certain care leavers, people receiving qualifying disability benefits and people affected by domestic abuse.
Housing entitlement can therefore vary considerably between two claimants of the same age.
How Does The Under-25 Rate Affect Young Parents?
A parent under 25 can still receive the lower standard allowance even though raising a child creates substantial additional household costs.
However, Universal Credit is not limited to the standard allowance.
A qualifying parent may receive additional support through child elements, childcare support and housing costs.
For 2026/27, eligible childcare support can cover up to 85% of qualifying childcare expenses within the applicable monthly limits.
Additional amounts may also be available where a child has a qualifying disability.
As a result, two young parents of the same age can receive very different Universal Credit payments depending on their children, childcare costs, earnings, rent and other household circumstances.
The lower age-based standard allowance should therefore not be viewed as the claimant’s complete Universal Credit entitlement.
What Happens To Universal Credit When You Turn 25?
Reaching the age of 25 can affect the standard allowance used in a Universal Credit calculation.
For 2026/27, the standard allowance categories are £338.58 for a single claimant under 25 and £424.90 for a single claimant aged 25 or over.
For couples, £528.34 applies where both partners are under 25, while £666.97 applies where one or both are aged 25 or over.
Universal Credit is calculated using monthly assessment periods, so claimants should check the statement covering their change in circumstances rather than assuming the increase will appear as a separate payment immediately on their birthday.
If the correct age-related allowance does not appear when expected, the claimant can raise the issue through their Universal Credit account.
Conclusion
The Universal Credit under 25 penalty is not an official DWP sanction. It describes the lower standard allowance that applies to younger claimants under the current Universal Credit structure.
In 2026/27, a single claimant under 25 receives £338.58 per month compared with £424.90 for someone aged 25 or over. This creates a difference of £86.32 each month or approximately £1,035.84 over 12 months.
Actual Universal Credit sanctions are separate and can reduce the standard allowance when relevant claimant commitments are not met without good reason.
Young claimants may also qualify for housing support, child elements, childcare assistance and other additions. Checking the complete Universal Credit calculation is therefore important when determining whether a payment is correct.
FAQs
Is Universal Credit Lower If You Are Under 25?
Yes. The 2026/27 standard allowance for a single claimant under 25 is £338.58 per month, compared with £424.90 for someone aged 25 or over.
How Much Universal Credit Does A Single Person Under 25 Get?
The standard allowance is £338.58 per month in 2026/27. Additional amounts may be available depending on housing costs, children, childcare, caring responsibilities and qualifying health circumstances.
How Much Is A Universal Credit Sanction For Someone Under 25?
The full daily sanction reduction for a single claimant under 25 is £11.10 in 2026/27. A lower daily reduction can apply in certain circumstances.
Does A Universal Credit Sanction Stop Housing Payments?
A sanction reduces the standard allowance. Eligible additional Universal Credit amounts for housing and children can continue to be included.
Can You Get A Hardship Payment If You Are Sanctioned?
Potentially. A claimant who cannot meet essential living costs because of a sanction may qualify for a recoverable hardship payment, which normally has to be repaid from future Universal Credit.
Does Universal Credit Increase When You Turn 25?
The standard allowance can move to the 25-or-over rate once the age requirement applies. The timing should be checked against the claimant’s Universal Credit assessment period and statement.
Can You Receive The Under-25 Rate And A Sanction Together?
Yes. The lower under-25 standard allowance and a Universal Credit sanction are separate rules, so both can affect the same claimant at the same time.