
Universal Credit Business Start-Up Support 2026: Grants, Eligibility And Application Process
 • October 25, 2025
•
1 Comment
Last Updated: 23.10.2026
Starting a business while receiving Universal Credit is possible, but the phrase Universal Credit Business Start-Up Grant can be misleading.
As of October 2026, there is no dedicated DWP grant under that name that provides every Universal Credit claimant with money to launch a business.
Instead, Universal Credit can continue supporting eligible people while they move into self-employment. Some may qualify for a start-up period where their actual earnings are used rather than the Minimum Income Floor.
Separate grants, government-backed loans and business support programmes may also provide money for equipment, marketing, premises or other approved costs.
For someone trying to launch without a large amount of capital, keeping early expenditure under control is equally important.
Some businesses can be launched with relatively modest budgets, as shown by these ideas for starting a business with £1,000 in the UK.
Can Universal Credit Support You While You Build A Business?
Yes. You can continue claiming Universal Credit while becoming self-employed, provided you remain eligible for the benefit and correctly report your circumstances, income and expenses.
Once you tell Universal Credit that you are self-employed, you will normally have a self-employed interview with a work coach.
DWP uses this meeting to determine whether you are gainfully self-employed and whether you qualify for the start-up period.
To be considered gainfully self-employed, DWP says the work should normally be your main job or main source of income, organised, developed, regular and expected to make a profit.
Evidence could include invoices, bank statements, customers, contracts, advertising and a business plan.
Universal Credit therefore provides income support rather than start-up capital. If you need money to purchase equipment or launch the business, you generally need to consider a separate grant, loan or other funding programme.
What Business Support Can You Get While Claiming Universal Credit?
The most important support available through Universal Credit itself is the start-up period.
If you qualify, it can give you up to 12 months to establish your business. During that period, DWP uses your actual monthly earnings to calculate Universal Credit rather than applying the Minimum Income Floor.
You can also receive support from a work coach experienced in self-employment.
Other support may come from outside Universal Credit, including:
- Government-Backed Start Up Loans: Loans for eligible new and early-stage UK businesses
- Local Business Grants: Funding offered by councils and regional business programmes
- The King’s Trust Funding: Grants and loans for eligible entrepreneurs participating in its programmes
- Access To Work: Support with additional work-related costs arising from a disability or health condition
- Sector-Specific Grants: Funding for areas such as innovation, technology, sustainability and manufacturing
Those who want to limit their reliance on borrowing may also consider low-cost business ideas with relatively small start-up requirements while they establish consistent income.
What Requirements Must You Meet To Get Business Start-Up Support?
There is no single eligibility test covering every UK business grant. Each funding organisation establishes its own requirements.
For Universal Credit’s start-up period, DWP will consider your self-employment circumstances and whether you are actively trying to increase earnings.
For separate business grants, common requirements can include:
- Eligible Location: Your home or business may need to be within a particular council or funding area
- Eligible Business Stage: Some programmes only support pre-start businesses or firms within their first few years
- Viable Business Idea: The provider may expect evidence that genuine customer demand exists
- Business Plan: You may need to explain the business model, target customers, costs and growth plans
- Cash Flow Forecast: Many programmes want to understand expected income and expenditure
- Approved Spending Purpose: Funding normally has to be used for specific eligible business costs
- Supporting Evidence: Quotes, bank statements, registrations or proof of trading may be requested
- Matching Funds: Some grants require the business owner to contribute part of the project cost
The King’s Trust, for example, says applicants for its Start Up funding should have considered their business goals, undertaken market research, developed their business plan and prepared a cash flow forecast.
Funding remains subject to approval and assessment criteria.
Testing whether customers actually want your proposed product or service before applying can strengthen a business case.
Reviewing successful small business models currently operating in the UK can also help when assessing demand and startup costs.
How Does The Universal Credit Start-Up Period Work?
An eligible self-employed claimant can receive a start-up period lasting up to 12 months.
During this period:
- Actual Earnings Are Used: Universal Credit is generally calculated from the self-employed earnings you actually report
- Minimum Income Floor Does Not Apply: DWP does not assume that you earned the MIF during the eligible start-up period
- Other Work Requirements Are Relaxed: You do not normally need to look for other employment while the start-up period applies
- Work Coach Support Is Available: A trained work coach can provide support during the business-building period
- Regular Reviews Are Required: You need to attend appointments and demonstrate that you are actively increasing your business earnings
DWP can end the start-up period early if you fail to attend required meetings or cannot demonstrate that you are taking active steps to grow the business.
A second start-up period is possible in limited circumstances. Current guidance says it must normally be more than five years since the previous start-up period and the new business must involve a different trade, profession or vocation.
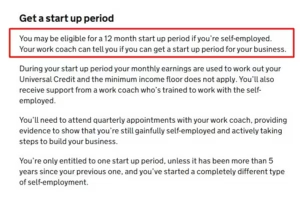
GOV.UK confirms that eligible self-employed claimants can receive a 12-month start-up period during which the Minimum Income Floor does not apply.
What Do You Need To Apply For A Business Grant While On Universal Credit?
Claiming Universal Credit does not automatically qualify you for a separate business grant. You will need to satisfy the rules of whichever funding programme you apply to.
Prepare the application before the funding deadline and make sure your proposed spending fits the scheme.
Common documents include:
- Business Plan: Explaining what the business does and how it will generate revenue
- Cash Flow Forecast: Showing expected income, expenditure and funding requirements
- Proof Of Identity: Confirming who is applying
- Proof Of Address: Particularly important for geographically restricted grants
- Business Bank Details: Where required by the funding provider
- Supplier Quotes: Showing how much equipment or services will cost
- Market Research: Demonstrating demand for the proposed business
- Proof Of Trading: Such as invoices, contracts or sales where the business has already started
- HMRC Information: Where registration or a UTR is relevant to the scheme
Universal Credit also requires evidence at the self-employed interview. DWP says this can include invoices, receipts, bank statements, customer or supplier records, contracts, websites, social media activity, marketing materials and business certificates.
If you have not settled on a business model yet, researching potential markets before seeking funding is important. These steps for developing a business idea from scratch can help with that early validation stage.
What Happens After A Business Grant Is Approved?
Getting an approval notice does not always mean unrestricted money will immediately appear in your bank account.
The process depends on the grant provider and the terms of the specific scheme. You should read the award letter carefully before committing to expenditure.
A typical post-approval process may include:
- Receive The Funding Decision: The provider confirms the amount approved and eligible project costs.
- Accept The Grant Conditions: You may need to sign an agreement accepting spending, reporting and project requirements.
- Provide Final Evidence: Some providers may require bank details, supplier quotations or additional documentation before releasing funds.
- Purchase Approved Items: Money must normally be spent only on expenditure approved by the grant provider.
- Submit A Payment Claim: Some grants are paid upfront while others reimburse you after you have paid eligible costs.
- Keep Receipts And Invoices: You may need them to demonstrate exactly where the grant money went.
- Complete Monitoring Requirements: The provider may request evidence of business progress, jobs created, equipment purchased or other agreed outcomes.
Do not assume you can change what the grant is being used for after approval. If circumstances change, contact the provider before moving money between spending categories.
Some grants also operate on a match-funding basis, meaning the business pays a percentage of the project cost itself. Approval therefore does not necessarily mean the grant provider covers the entire project.
Does Receiving A Business Grant Affect Your Universal Credit?
It can.
DWP’s current guidance says self-employed claimants must report business grants or subsidies as business income where they are treated as taxable income by HMRC.
That means receiving a grant does not automatically produce the same Universal Credit result in every case. Its tax treatment and purpose matter.
You should maintain the award letter, payment records and information showing how the grant has been treated.
Universal Credit requires self-employed claimants to report income and expenses every month, including months where there was no income or expenditure. Payments can be delayed if the required monthly information is not submitted.
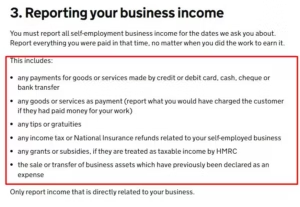
DWP guidance confirms that grants and subsidies treated as taxable income by HMRC must be included when reporting self-employment income.
How Does Self-Employment Income Affect Your Universal Credit Payments?
Universal Credit is assessed monthly.
For self-employed people, DWP generally works out earnings by adding business income received during the reporting period and deducting allowable business expenses. Different rules can apply when the Minimum Income Floor is in force.
Some households also qualify for a work allowance before earnings begin reducing Universal Credit.
For 2026/27, the monthly work allowance is:
Circumstances Monthly Work Allowance
Eligible Claimant Receiving Housing Support £427
Eligible Claimant Without Housing Support £710
A work allowance generally applies where the claimant or partner is responsible for a child or has limited capability for work. Above the relevant allowance, Universal Credit normally reduces by 55p for every £1 of earnings.
Self-employed income can fluctuate significantly. If your business makes a loss, current DWP guidance says that loss can be carried forward and offset against later self-employed profits until it has been accounted for or you stop being self-employed.
Very high earnings can also create surplus earnings. DWP currently applies surplus earnings rules where earnings are £2,500 or more above the level at which Universal Credit entitlement falls to zero.
Accurate financial records therefore matter from the first day of trading. Self-employed people with higher qualifying income should also be aware of the Making Tax Digital rules for self-employed workers from 2026 onwards.
What Business Expenses Can You Report To Universal Credit?
Allowable expenses reduce the self-employed earnings figure used by Universal Credit, but an expense must generally be appropriate, necessary and reasonable for the business.
Depending on the circumstances, allowable expenditure can include:
- Business Premises Costs: Rent, utilities, security, cleaning and qualifying maintenance
- Office And Equipment Costs: Software, stationery, tools, equipment and business-related communications
- Stock And Materials: Goods for resale and raw materials used by the business
- Marketing Costs: Advertising, promotion and eligible free samples
- Professional Costs: Accounting, legal services and relevant professional subscriptions
- Business Insurance: Eligible insurance connected with the business
- Staff Costs: Wages, qualifying subcontractor costs and employer contributions
- Business Travel: Qualifying travel costs under the relevant expense rules
- Tax And National Insurance: Certain payments actually made during the reporting period
- Pension Contributions: Payments into qualifying registered pension arrangements
There are restrictions. For example, capital repayments on a business loan cannot be deducted as a Universal Credit business expense. Business loan interest can be reported subject to a maximum of £41 per month under current guidance.
Universal Credit expense rules should not automatically be assumed to be identical to HMRC tax rules.
You should also keep appropriate tax records separately. Understanding when a Self Assessment tax return needs to be submitted can help prevent Universal Credit reporting and tax responsibilities from becoming mixed up.
What Grants And Funding Can You Apply For Instead?
There is no universal replacement grant that every person claiming Universal Credit can receive. The most suitable funding depends on age, location, business stage, sector and personal circumstances.
Start Up Loans
Start Up Loans are government-backed personal loans for business purposes, not grants.
From 6 April 2026, successful applicants can borrow between £500 and £25,000 at a fixed annual interest rate of 7.5%, generally repayable over one to five years.
First-loan applicants can now include eligible businesses trading for up to 60 months. First-loan recipients also receive 12 months of free mentoring.
Applicants normally need to satisfy eligibility and affordability checks and provide business planning information.
The King’s Trust Enterprise Funding
Eligible entrepreneurs supported through The King’s Trust Enterprise programme may have access to funding.
The King’s Trust currently says qualifying participants can apply for up to £30,000 through a combination of funding, including a Start Up Grant of up to £5,000 and a Start Up Loan of between £500 and £25,000. Approval is subject to assessment criteria.
The grant element does not need to be repaid.
Access To Work
Access to Work can provide practical and financial support where a disability or health condition creates additional work-related costs.
It can support someone moving into self-employment or starting a business, but it does not cover ordinary business start-up costs.
The grant can instead contribute towards additional support needed to carry out the work. GOV.UK also states that Access to Work payments do not affect other benefits.
Local Council And Regional Business Grants
Local authorities regularly operate business grants tied to a specific geographical area, sector or business stage.
Eligibility can change significantly between schemes.
A grant may require applicants to:
- Operate Within The Funding Area
- Have Traded For Less Than A Set Period
- Create Or Protect Jobs
- Invest Their Own Matching Funds
- Purchase Approved Equipment
- Meet Environmental Or Economic Objectives
- Complete Business Support Before Funding
The GOV.UK business finance service lists current funding programmes and allows businesses to filter support by business stage and type.
Government Find A Grant Opportunities
The government’s Find a Grant service provides another way to search available funding.
Users can search and filter grants, check eligibility requirements and review application instructions. Funding changes regularly, so checking current opportunities is more useful than relying on an old list of grants that may have already closed.
What Happens When The Universal Credit Start-Up Period Ends?
The end of the start-up period can significantly change how Universal Credit is calculated.
Where you remain gainfully self-employed, the Minimum Income Floor may begin to apply.
The Minimum Income Floor is based broadly on what an employed person in comparable circumstances would earn at the applicable National Living Wage or National Minimum Wage after Income Tax and National Insurance.
If your actual earnings are higher than your Minimum Income Floor, DWP uses your actual earnings.
If your earnings are lower, DWP can use the Minimum Income Floor instead. This can reduce your Universal Credit even though your business did not actually earn that amount.
This makes the 12-month period important for establishing regular customers and improving revenue.
Before the period ends, it is sensible to review:
- Monthly Revenue: Whether sales are increasing consistently
- Business Costs: Whether unnecessary expenditure can be reduced
- Customer Pipeline: Whether enough future work is booked
- Pricing: Whether prices produce a sustainable margin
- Cash Reserve: Whether the business can handle weak months
- Alternative Income: Whether additional employment may be needed
- Business Viability: Whether continuing the current model is financially realistic
The aim should be to build a business that can eventually support you without depending permanently on benefit payments.
Conclusion
A Universal Credit Business Start-Up Grant is not a single nationwide grant that Universal Credit claimants can simply apply for.
The practical support comes from a combination of the Universal Credit start-up period and separate business funding schemes.
The first step is to report your self-employment correctly and establish whether you qualify for the start-up period. From there, prepare a strong business plan, cash flow forecast and evidence of genuine trading activity before applying for outside funding.
If a grant is approved, follow its spending and reporting conditions carefully and keep invoices, receipts and payment records. You should also report relevant business income and expenses accurately to Universal Credit each month.
The strongest approach is to use Universal Credit as temporary financial support while building a business capable of producing sustainable income, rather than treating Universal Credit itself as a source of startup capital.
FAQs
Can Universal Credit Give You Money To Start A Business?
There is no dedicated Universal Credit Business Start-Up Grant that automatically provides startup capital. Universal Credit can support eligible living costs while you establish self-employment, while separate funding programmes may provide grants or loans.
Can You Claim Universal Credit While Starting A Business?
Yes. Eligible claimants can start a business while receiving Universal Credit. You must report your self-employment and provide the required monthly income and expense information.
What Requirements Do You Need To Meet For A Business Grant?
Requirements depend on the grant. Common conditions include location, business stage, an eligible spending purpose, a viable business plan, financial forecasts and evidence showing how the funding will be used.
How Long Does It Take To Receive A Grant After Approval?
There is no universal payment timescale. Some schemes pay after the grant agreement is completed, while others reimburse approved expenditure after invoices and proof of payment have been submitted.
Do You Have To Repay A Business Start-Up Grant?
Normally, a genuine grant does not need to be repaid if all conditions are met. Repayment may potentially be required where grant terms are breached, funds are misused or the award was made based on incorrect information.
Does A Business Grant Affect Universal Credit?
It can. DWP says business grants or subsidies treated as taxable income by HMRC should be reported as self-employment business income.
What Happens If Your Business Makes A Loss?
DWP’s current guidance says a self-employed loss can be carried forward and balanced against future profits until the loss has been accounted for or you stop being self-employed.

[…] other forms of support, while people receiving benefits should understand the actual rules around a Universal Credit business start-up grant and available alternatives rather than assuming a specific grant automatically […]