Working From Home Tax Relief 2026/27: Can You Still Claim?
 • October 25, 2025
Working from home tax relief has changed significantly in 2026.
What began as a relatively small allowance for employees facing additional household costs became much more widely used during the pandemic, but the employee-claimed relief has now reached its end.
The important point is that the change does not erase every opportunity connected with homeworking costs.
Eligible employees may still be able to claim relief for earlier tax years, while employers can continue reimbursing qualifying homeworking expenses under separate tax-free rules.
The history is also worth understanding. The flat-rate amount did not increase every year.
It remained at £4 per week for several years, increased to £6 from April 2020 and stayed at that level until the employee deduction was removed from 6 April 2026.
This guide explains what changed, which previous years remain open for claims, how much tax relief could be recovered, what evidence HMRC now expects and what employers can still pay towards working from home costs.
Can You Still Claim Working From Home Tax Relief In 2026/27?
You cannot make a new employee working from home tax relief claim for expenses incurred during the 2026/27 tax year.
From 6 April 2026, the government removed the Income Tax deduction previously available when employees were required to work from home and their employer did not reimburse their additional household costs.
This applies even where homeworking is genuinely required by the job.
However, this does not prevent you from claiming for an earlier tax year that remains within HMRC’s four-year time limit.
As of the 2026/27 tax year, eligible claims may still potentially be made for:
- 2022/23 Tax Year
- 2023/24 Tax Year
- 2024/25 Tax Year
- 2025/26 Tax Year
You must have satisfied the eligibility conditions that applied during the tax year being claimed.
A successful previous-year claim may result in a repayment or another adjustment by HMRC. Processing times depend on the particular claim and whether further checks are required, so the timing can differ from other types of HMRC tax rebates and repayments.
What Changed To Working From Home Tax Relief From 6 April 2026?
Until 5 April 2026, an eligible employee who had to work from home could potentially claim Income Tax relief for additional household expenses that were not reimbursed by their employer.
That employee deduction ended on 6 April 2026.
The change means an employee cannot personally claim homeworking household expenses from HMRC for 2026/27 simply because their employer requires them to work remotely.
The abolition specifically affects non-reimbursed homeworking expenses. It does not prevent an employer from paying qualifying homeworking expenses under the separate employer reimbursement rules.
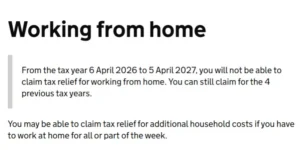
GOV.UK confirms that working from home tax relief is unavailable for 2026/27 but claims can still be made for the previous four tax years.
Employees who previously had relief incorporated into their PAYE arrangements should therefore check their current position carefully.
Changes involving allowances, deductions or benefits can affect PAYE calculations, so understanding why an HMRC tax code changes can also help when reviewing a payslip.
Has Working From Home Tax Relief Increased Every Year?
No. Working from home tax relief did not increase constantly from one tax year to the next.
The flat-rate employee allowance remained unchanged for long periods.
| Tax Years | Flat-Rate Amount | Position |
|---|---|---|
| 2011/12 To 2019/20 | £4 Per Week | Historical Employee Rate |
| 2020/21 To 2025/26 | £6 Per Week | Increased Flat Rate |
| 2026/27 Onwards | No Employee Deduction | Relief Abolished |
HMRC’s employment guidance confirms that the employee flat rate was £4 per week from 2011/12 through 2019/20 before increasing to £6 per week from 6 April 2020.
£4 Per Week From 2011/12 To 2019/20
For much of the previous decade, eligible employees could use a £4 weekly flat rate rather than calculating every additional household cost individually.
A worker eligible for an entire 52-week year could therefore base the historical deduction on:
£4 × 52 = £208
The actual amount of tax saved would then depend on the taxpayer’s Income Tax rate rather than the employee simply receiving £208 from HMRC.
Increase To £6 Per Week From 2020/21
Budget 2020 increased the flat-rate deduction from £4 to £6 per week from April 2020.
The timing coincided with a huge expansion in homeworking during the COVID-19 period, although the £6 rate itself remained in place after the temporary pandemic arrangements ended.
At £6 per week, a full 52-week year’s qualifying expense amounted to:
£6 × 52 = £312
The flat rate then remained at £6 through the final eligible employee tax year of 2025/26. There was no annual inflation-linked increase.
End Of Employee Tax Relief From 6 April 2026
Instead of being increased again for 2026/27, the employee deduction was removed altogether.
This means the history of the flat-rate employee relief is relatively simple:
£4 → £6 → Abolished
Employers, however, still have separate rules allowing qualifying tax-free homeworking payments, including the £6 weekly guideline rate.
Why Was Working From Home Tax Relief Abolished?
The government announced the change at Budget 2025, with the new rule taking effect from 6 April 2026.
HMRC said the policy was intended to address concerns about non-compliance and fairness within the tax system. According to the government’s tax information and impact note, more than half of the homeworking claims checked were considered ineligible.
The government estimated that approximately 300,000 individuals would be affected by removing the relief.
For people who previously claimed the full £6 weekly amount, the estimated annual tax effect was approximately:
- Basic-Rate Taxpayer – £62
- Higher-Rate Taxpayer – £124
These figures represent the approximate tax saving being lost rather than a £312 payment being taken away.
The government also stated that the change was not expected to create a direct administrative burden for employers because the separate employer reimbursement rules continue.
Which Previous Tax Years Can You Still Claim For?
The abolition does not automatically prevent claims relating to earlier years.
HMRC allows qualifying job-expense claims to be made within four years from the end of the tax year being claimed.
In October 2026, that leaves the following years potentially available:
| Tax Year | Employee WFH Relief | General Claim Deadline |
|---|---|---|
| 2022/23 | Potentially Available | 5 April 2027 |
| 2023/24 | Potentially Available | 5 April 2028 |
| 2024/25 | Potentially Available | 5 April 2029 |
| 2025/26 | Potentially Available | 5 April 2030 |
| 2026/27 | Not Available | Not Applicable |
The 2025/26 tax year is therefore particularly important because it was the final tax year in which qualifying employee homeworking expenses could generate this deduction.
A four-year claim limit should not be confused with other HMRC compliance periods. Different rules determine how far back HMRC can investigate tax affairs, depending on the circumstances.
Who Can Make A Backdated Working From Home Tax Relief Claim?
A person cannot claim simply because they happened to work from home.
For the eligible historical years, HMRC’s normal post-pandemic rule required the employee to have to work from home.
Examples could include situations where:
- No Employer Office Was Available – The employer did not operate an office where the employee could reasonably perform the job
- The Job Required Homeworking – The duties genuinely required the employee to work from home
- The Employee Lived Too Far From The Office For The Job Arrangement – The circumstances of the employment required work to be carried out remotely
HMRC specifically states that choosing to work from home is not enough.
For example, a claim generally would not qualify merely because an employment contract gives a worker the option of working remotely.
Similarly, an employee does not become eligible merely because an employer’s office is occasionally full.
Does Hybrid Working Qualify For A Backdated Claim?
Hybrid working does not automatically qualify or disqualify an employee.
The important question for the historic employee relief is why the person worked from home.
If an employee simply preferred working from home for two or three days each week while a workplace remained available, that voluntary arrangement would generally not satisfy the historical employee deduction conditions.
If the employee genuinely had to work at home for part of the week because of the requirements of the employment, the position may have been different.
Employees therefore need to look beyond the number of days spent at home and establish whether working remotely was genuinely required.
How Much Working From Home Tax Relief Can You Claim For Previous Years?
For eligible previous years, employees could generally use either:
- £6 Weekly Flat Rate
- Actual Additional Costs
These figures represented deductible expenses. They were not direct cash payments of £6 every week.
£6 Per Week Flat Rate
The £6 weekly method was the simpler option.
If you qualified for the full 52 weeks:
£6 × 52 = £312 qualifying expense
The amount actually saved depended on your Income Tax rate.
For example:
| Income Tax Rate | Qualifying Annual Expense | Approximate Tax Relief | |
|---|---|---|---|
| 20% | £312 | £62.40 | |
| 40% | £312 | £124.80 | |
| 45% | £312 | £140.40 | |
A basic-rate taxpayer therefore did not receive £312 from HMRC. A full-year claim based on £312 of qualifying expenditure produced £62.40 of tax relief at a 20% tax rate.
HMRC itself illustrates this principle by explaining that a 20% taxpayer claiming £6 receives £1.20 of tax relief for that week.
Actual Additional Household Costs
Some eligible employees could instead claim the actual additional amount they spent because they had to work from home.
This route could potentially produce a larger allowable expense, but it required evidence and a defensible calculation.
An employee could not simply take a general household bill and claim an arbitrary percentage.
The expenditure had to represent additional qualifying costs caused by carrying out employment duties at home.
What Working From Home Expenses Could Employees Claim?
For qualifying historical claims, HMRC recognised additional costs directly connected with working at home.
Examples included:
- Gas And Electricity – Additional heating and electricity attributable to the work area
- Business Telephone Calls – Additional call costs incurred specifically for work
- Other Genuine Additional Costs – Where the employee could demonstrate that the expense arose because the employment duties were carried out at home
However, ordinary costs that would have existed anyway were generally excluded.
HMRC’s current working-from-home guidance specifically states that employees cannot claim for items used for both private and business purposes, giving rent and broadband access as examples.
The distinction is between an additional employment cost and an ordinary household cost that the employee would have paid regardless of where they worked.
What Evidence Does HMRC Require For A Backdated Claim?
Evidence has become particularly important for recent backdated claims.
HMRC introduced strengthened employment-expense evidence requirements from October 2024 after identifying a growing number of ineligible claims.
For a working from home claim covering 2022/23 or later, you generally need evidence showing that you were required to work from home.
Suitable evidence may include:
- Employment Contract – Showing that homeworking was required
- Employer Letter Or Document – Explicitly confirming that the employee had to work from home
- Evidence Of Actual Costs – Required where claiming more than the £6 weekly flat-rate amount
There is an important distinction between evidence of eligibility and evidence of spending.
If you claim the £6 weekly amount for 2022/23 or later, you need evidence that you had to work from home, but you do not need receipts proving £6 of expenditure for every week.
If you claim your actual costs instead, you also need supporting evidence such as bills or receipts.
Keeping accurate records can also be useful more broadly when dealing with HMRC because employment expense claims may be checked before relief is granted.
How Do You Claim Working From Home Tax Relief For Previous Tax Years?
The claim route depends on your circumstances and how you normally deal with HMRC.
HMRC Online Claim
HMRC provides an online service through which eligible PAYE employment-expense claims and supporting evidence can be submitted.
The online process asks for information about the expenses being claimed and whether you satisfy the eligibility rules.
You should have relevant employment details and supporting evidence ready before starting.
Form P87
A postal claim can be made using HMRC’s P87 form where the relevant conditions are met.
HMRC says postal claims must use the official P87 form and that claims may be made this way where:
- The Claim Is Within Four Years – From the end of the relevant tax year
- Annual Expenses Are £2,500 Or Less – Larger expense claims generally require Self Assessment
- Income Tax Was Paid – There must normally be tax against which relief can be given
Working from home expense claims cannot be made by telephone.
Self Assessment
If you already complete a Self Assessment tax return, HMRC says the employment expense claim should be made through the tax return.
People completing Self Assessment should also make sure they use the correct tax year and meet the relevant filing requirements.
The normal deadlines and filing process are explained in more detail when considering when a UK Self Assessment tax return must be submitted.
Where a backdated expense claim generates money owed by HMRC, the repayment process can vary depending on the claim and any checks required.
Can Employers Still Pay Working From Home Expenses In 2026/27?
Yes. This is one of the most important distinctions in the new rules.
The government abolished the employee’s personal deduction for unreimbursed homeworking expenses, but it did not abolish the existing exemption that allows employers to reimburse qualifying additional homeworking costs.
Where the necessary homeworking conditions are met, an employer can continue making qualifying payments without deducting Income Tax or National Insurance.
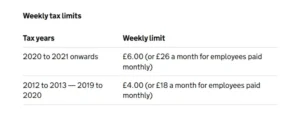
GOV.UK confirms that employers can continue paying qualifying additional household costs, with a £6 weekly limit available without supporting evidence of the amount spent.
Can Employers Still Pay £6 Per Week Or £26 Per Month Tax-Free?
Yes, where the qualifying employer homeworking rules are met.
HMRC’s current guideline allows an employer to pay:
- £6 Per Week
- £26 Per Month For Monthly-Paid Employees
without needing evidence demonstrating the precise amount of additional household costs.
Unlike the old employee deduction, this employer reimbursement rule remains available after 6 April 2026.
This makes employer policy more important for workers who continue to incur additional costs while regularly working from home.
An employer is not automatically required by this tax rule to pay every employee £6 per week. The tax exemption determines how qualifying reimbursement can be treated, rather than creating a universal statutory entitlement to the payment.
What Happens If An Employer Pays More Than £6 Per Week?
The £6 weekly figure is a guideline, not an absolute maximum.
An employer can pay more where the employee’s genuine additional household expenses justify the higher amount.
However, supporting evidence is required.
If an employer pays more than the employee’s genuine additional household expenses, the excess generally counts as earnings and PAYE tax and Class 1 National Insurance must be dealt with through payroll.
For example, if documented additional household costs amount to £9 per week, an employer may potentially reimburse that amount where the relevant conditions are satisfied and suitable evidence is retained.
What Is The Difference Between Employee Tax Relief And Employer Reimbursement?
These two arrangements are easy to confuse because both have historically used a £6 weekly figure.
They are now very different.
| Rule | Employee Claim From HMRC | Employer Reimbursement |
|---|---|---|
| Available In 2026/27 | No | Yes, If Conditions Are Met |
| £6 Weekly Figure | Historical Only | Still Available |
| Who Provides The Benefit | HMRC Through Tax Relief | Employer |
| Evidence Above £6 | Historical Actual-Cost Claims Required Evidence | Employer Must Support Higher Payment |
| Current-Year Household Expense Deduction | Abolished | Separate Exemption Continues |
Before April 2026, an eligible employee whose employer did not reimburse all qualifying additional costs could potentially seek tax relief from HMRC.
From April 2026, that employee fallback has disappeared.
Employer reimbursement therefore becomes more significant for businesses with staff who regularly work remotely.
Does The 2026 Change Affect Self-Employed People?
The abolition discussed in this article concerns the employee deduction for non-reimbursed homeworking household expenses.
It should not be treated as the abolition of every homeworking expense rule for sole traders.
Self-employed people operate under different business-expense rules and generally calculate allowable expenses through their business records and Self Assessment rather than using the employee working from home relief discussed here.
This distinction becomes increasingly important as tax reporting changes for sole traders.
From April 2026, the first group of qualifying sole traders and landlords entered Making Tax Digital for self-employed people, which introduces digital record-keeping and quarterly reporting requirements for those within the relevant income thresholds.
Employees and self-employed workers should therefore avoid applying the rules for one group to the other.
Conclusion
Working from home tax relief did not increase year after year. The employee flat rate remained at £4 per week from 2011/12 to 2019/20, increased to £6 from 2020/21 and remained there until the employee deduction ended on 6 April 2026.
Employees cannot claim the relief for new 2026/27 homeworking expenses, but eligible claims for 2022/23 to 2025/26 may still be possible within HMRC’s four-year limits.
The biggest change is the separation between employees and employers.
Employees have lost the personal homeworking deduction, while employers can still reimburse qualifying additional homeworking costs, including up to £6 per week or £26 per month under the current guideline rules.
Frequently Asked Questions
Is Working From Home Tax Relief Still Available In 2026?
Employee working from home tax relief is not available for expenses incurred from 6 April 2026. Eligible employees can still make claims relating to the previous four tax years.
When Did Working From Home Tax Relief Increase From £4 To £6?
The employee flat-rate amount increased from £4 to £6 per week from 6 April 2020. It remained at £6 until the employee deduction ended from April 2026.
Can I Still Claim £6 Per Week For Working From Home?
You cannot make an employee claim for £6 per week for the 2026/27 tax year. However, eligible backdated claims may still use the £6 rate for earlier qualifying years, and employers can still make qualifying £6 weekly reimbursements.
How Far Back Can I Claim Working From Home Tax Relief?
HMRC generally allows qualifying employment expense claims within four years from the end of the relevant tax year. In 2026/27, this can leave 2022/23 through 2025/26 open depending on the claim date.
Can Hybrid Workers Claim Working From Home Tax Relief?
Hybrid working alone does not establish eligibility for a backdated employee claim. For the relevant historical years, the employee normally needed to be required to work from home rather than simply choosing to do so.
Does My Employer Have To Pay Working From Home Expenses?
The tax exemption does not itself force every employer to pay a homeworking allowance. However, employers can reimburse qualifying additional homeworking costs tax-free where the relevant HMRC conditions are met.
Do I Need Receipts For A Backdated Claim?
For the £6 flat-rate claim covering 2022/23 or later, HMRC requires evidence that you had to work from home, but receipts proving £6 of weekly expenditure are not required.
Claims based on actual expenditure require additional supporting evidence such as bills or receipts.